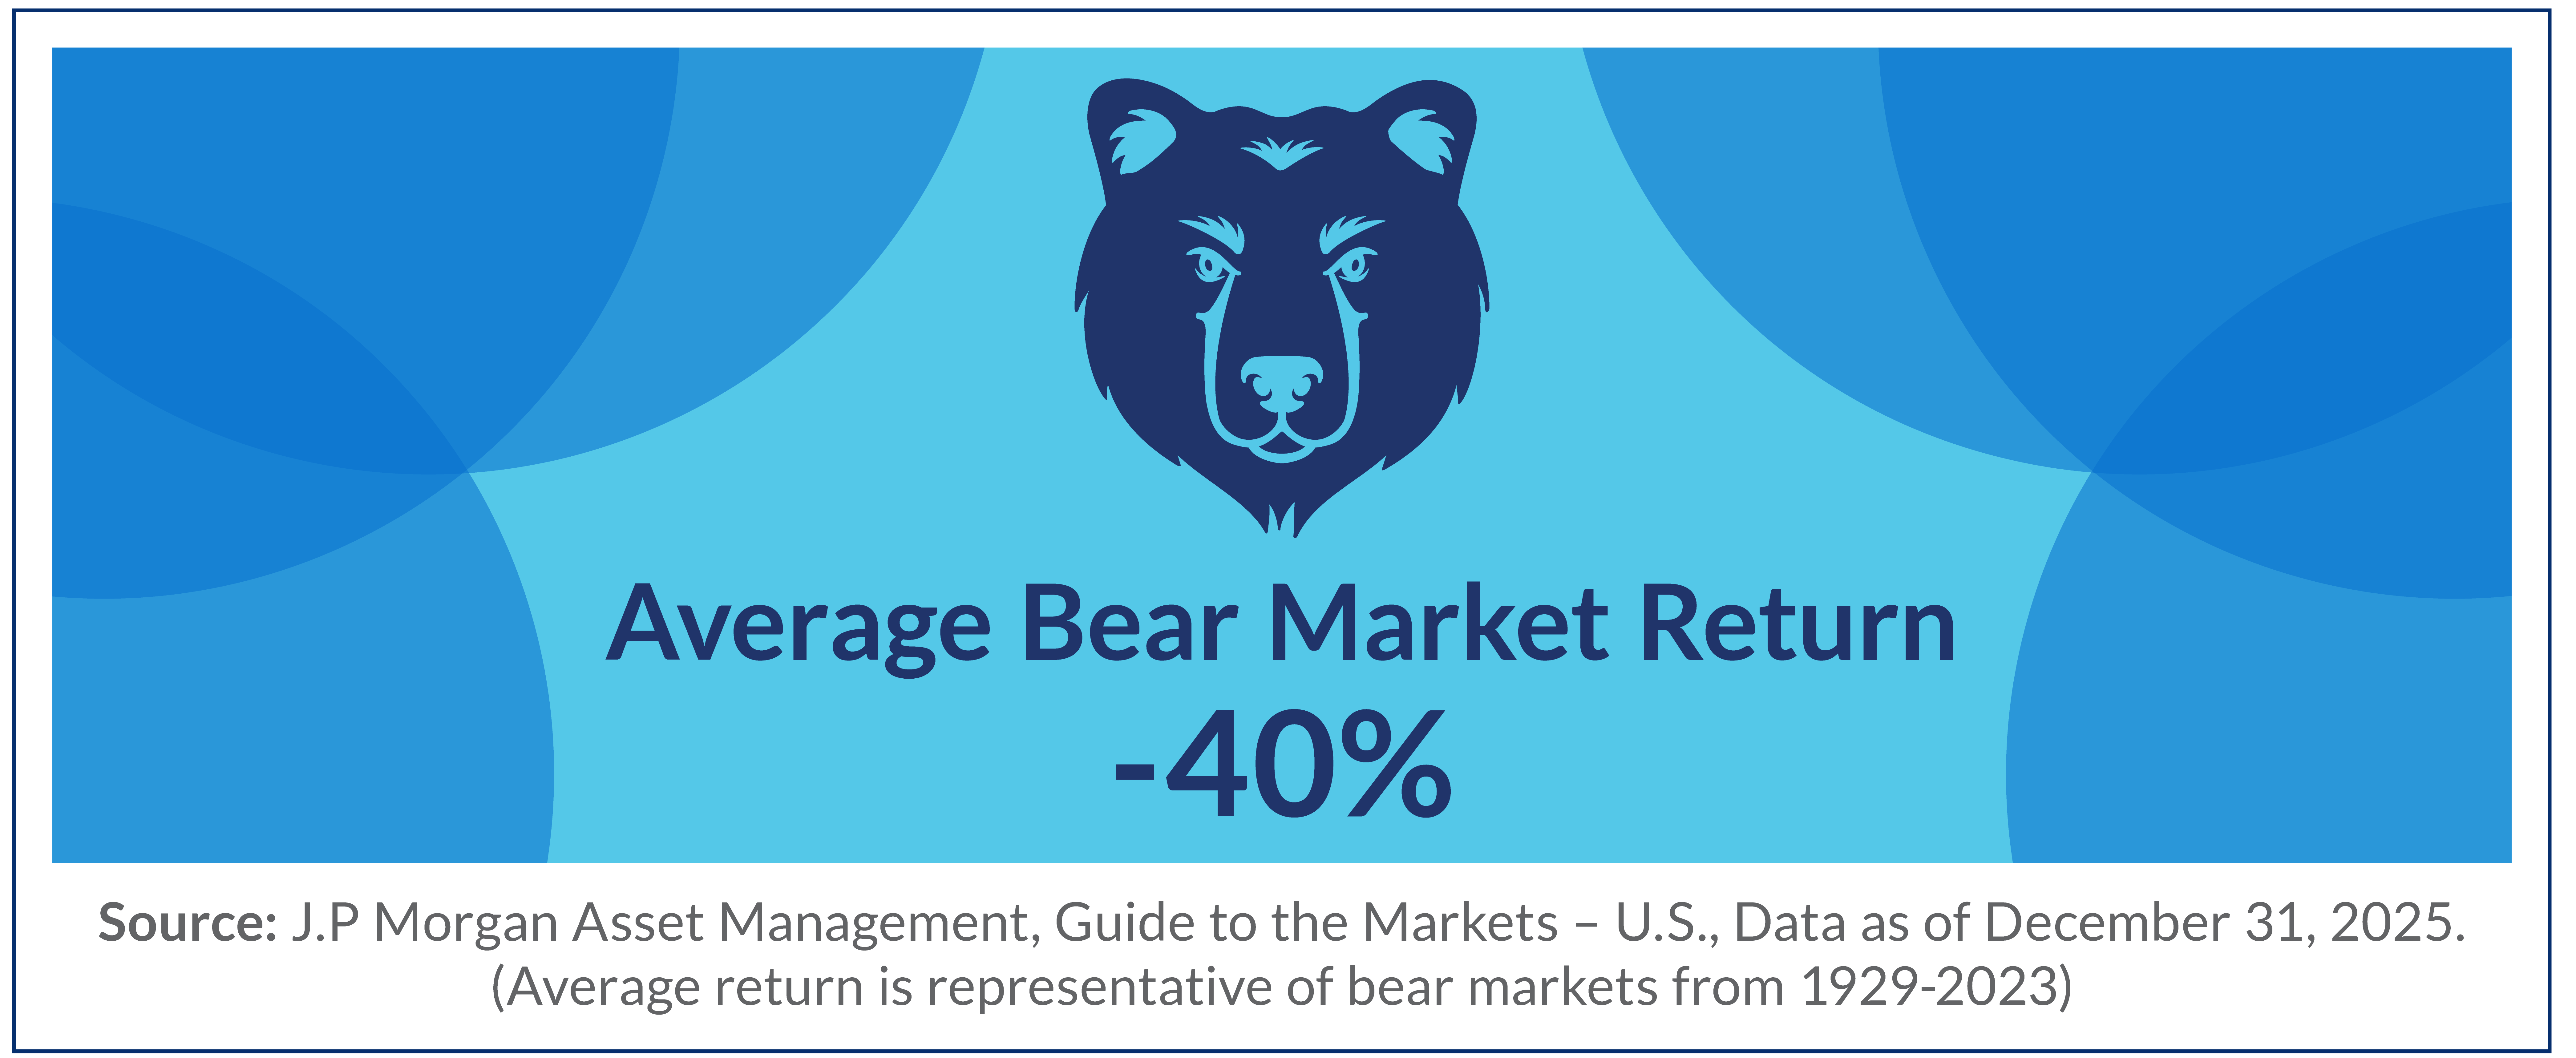
While market exposure can help with long-term growth goals, volatility risk will always be a reality for equity investors. Early 2020 marked the end of the longest-running bull market in modern history — and when long-run bull markets end, the decline can be dramatic.
Plus, recovering from a major market decline requires substantial gains and, in some cases, valuable time that retirees may not have.
If your clients can’t afford to weather the storm of a bear market, consider a lower-risk option.
Market insight: longevity risk and rising costs
Retirees are living longer, healthier lives than past generations. In fact, one in three 65-year-olds are projected to live to age 90 — and these longer life expectancies can put clients at risk of outliving their savings.
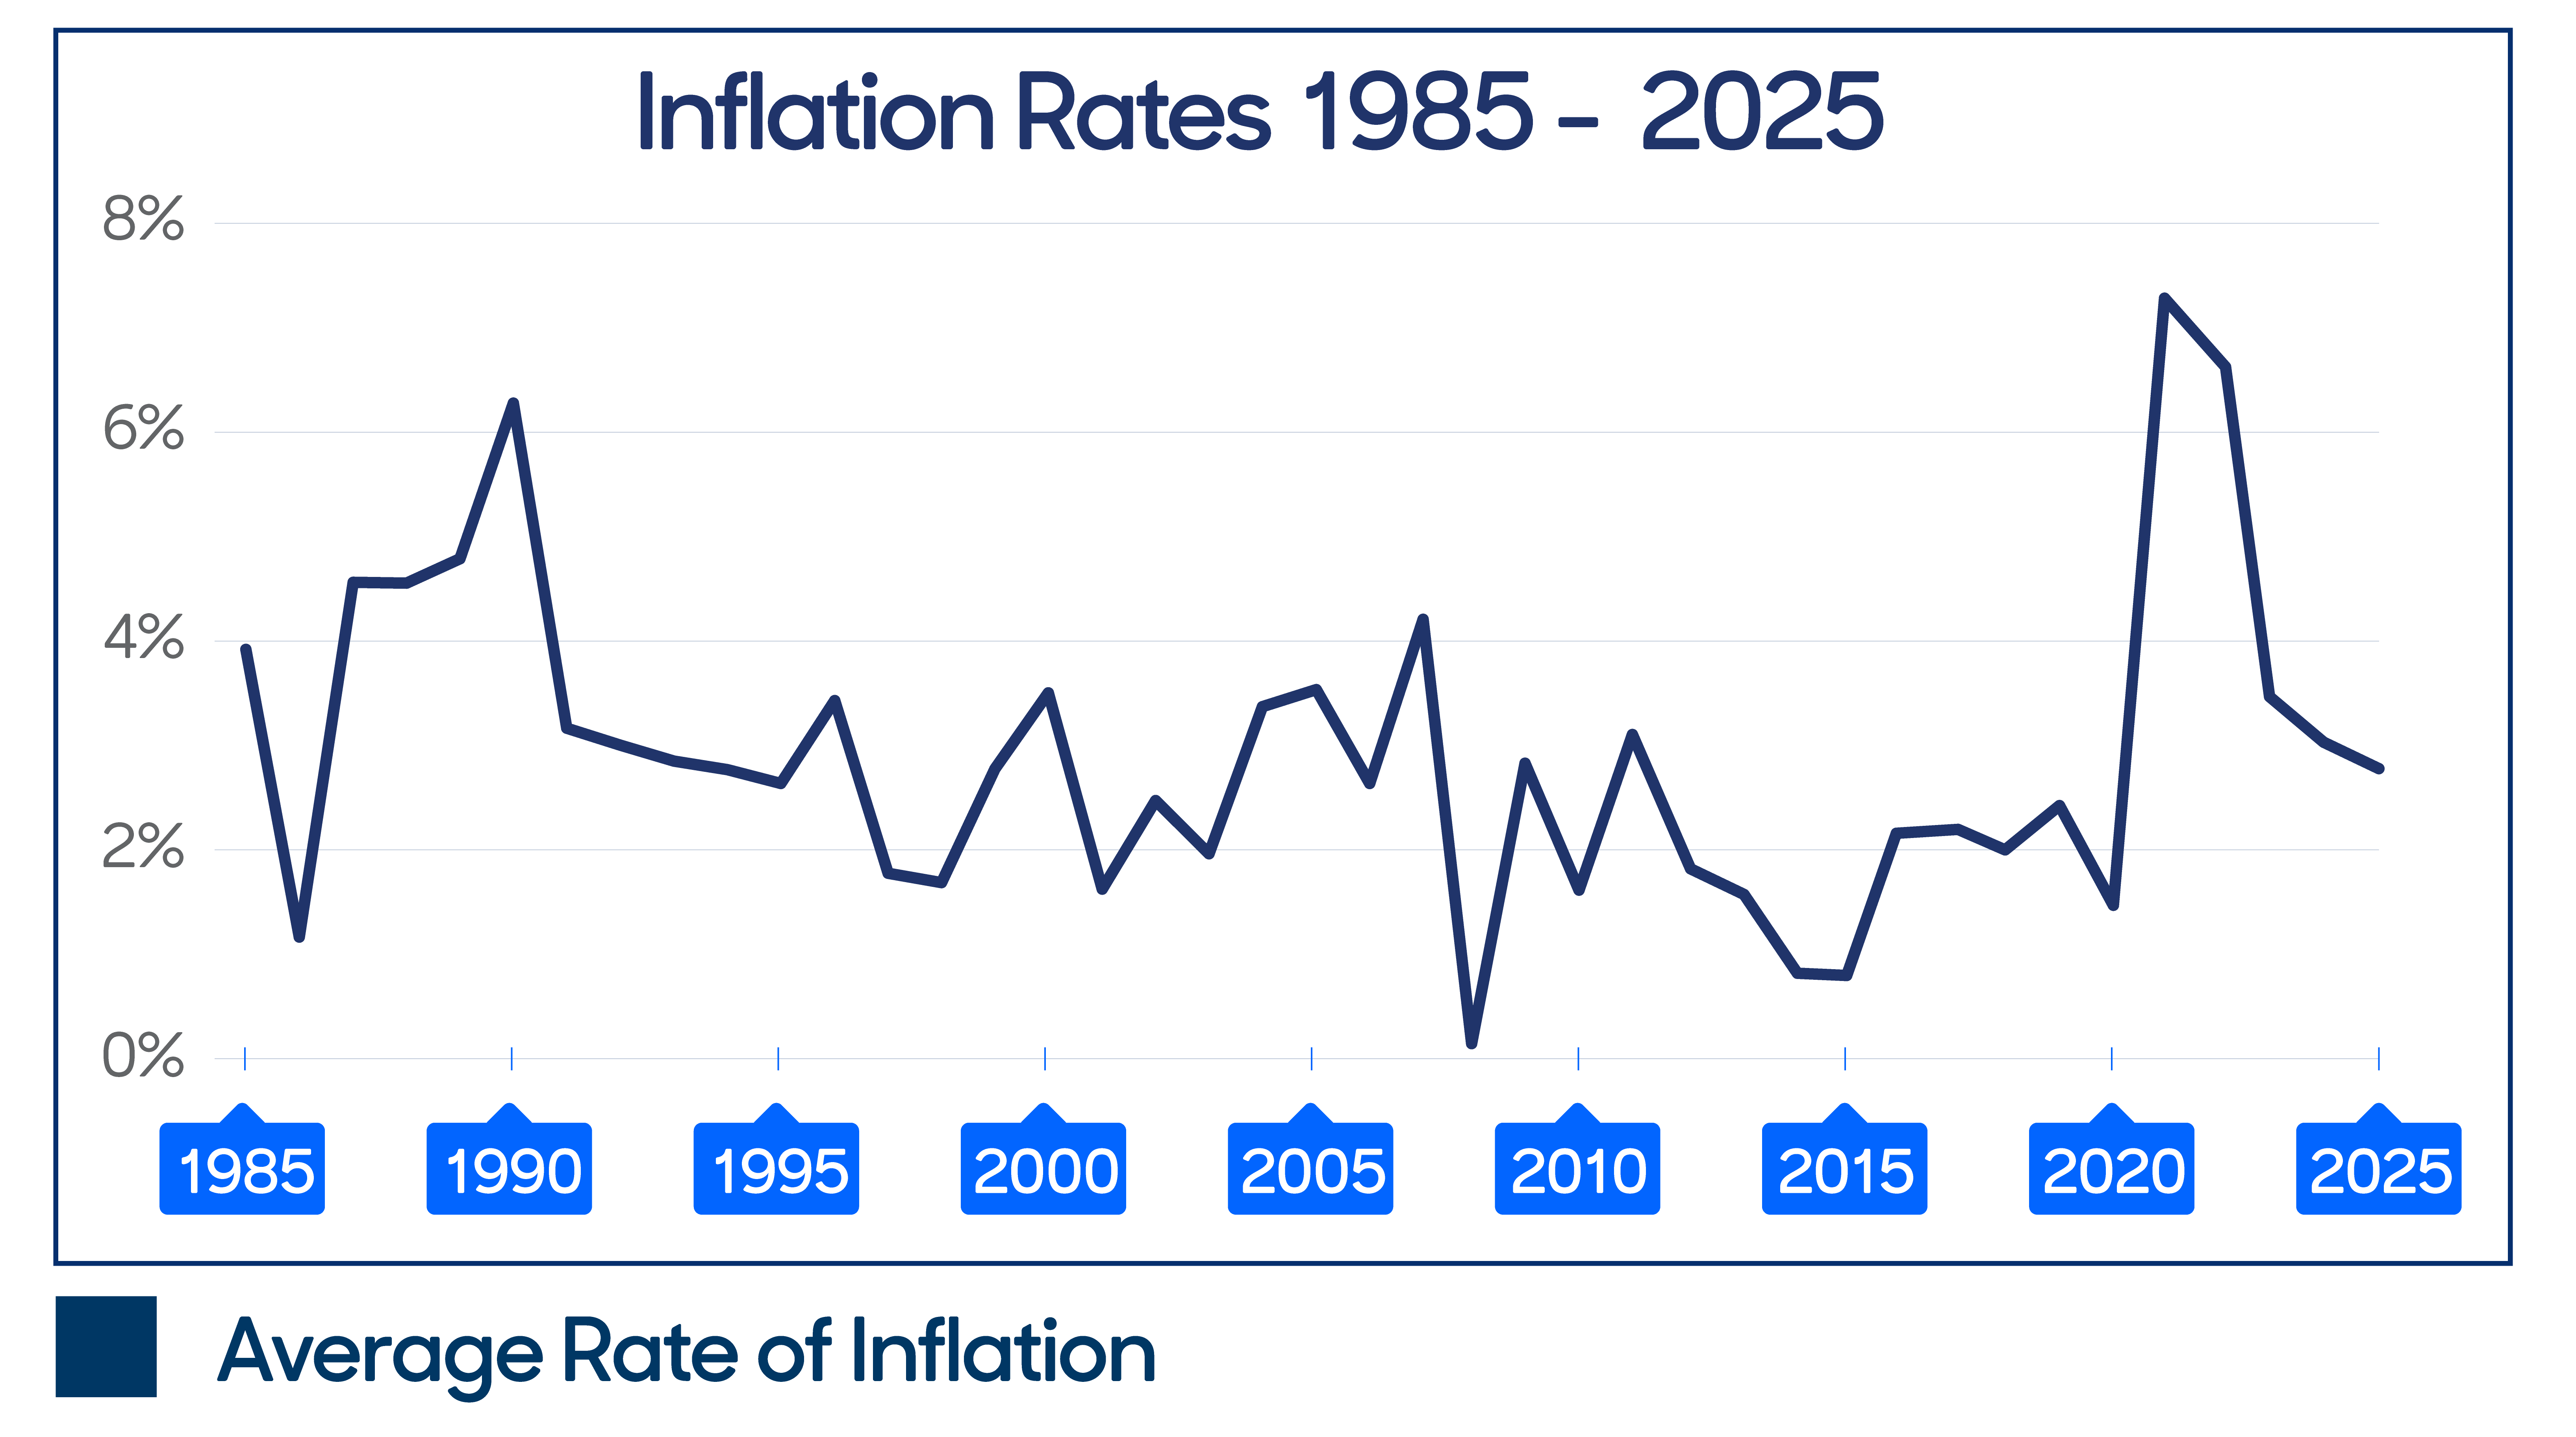
Some clients may turn to fixed income investments as a safe source of retirement income. But as record inflation reduces the value of a dollar, a portfolio weighted too heavily towards fixed income could fall behind. Consider an alternative source of contractual, guaranteed lifetime income for your clients.
The sequence of returns on a portfolio does not have an impact during the accumulation phase. However, once income is being drawn, early losses can have a lasting impact on portfolio value and withdrawal sustainability.
For clients seeking to mitigate sequence of returns risk, consider an alternative solution to help enhance portfolio resilience and supplement retirement income.